The Future of Accounting: Embracing AI and Machine Learning
December 10, 2025 | 18 min read
Accounting has always been a cornerstone of commerce, providing clarity and structure to financial transactions. From Luca Pacioli’s double-entry bookkeeping in 1494 to today’s digital platforms, the discipline continually evolves. Now, artificial intelligence (AI) marks another profound shift, promising to redefine accounting far beyond mere automation.
The accounting profession, with its many facets like bookkeeping, payroll, tax, audit, and advisory, is inherently labor-intensive and manual. This makes it an ideal candidate for automation, where accuracy and efficiency are paramount. AI technologies are now delivering both, transforming how financial professionals work.
Emerging technologies like Generative AI (GenAI), Optical Character Recognition (OCR), Intelligent Document Processing (IDP), and smart agents are taking over repetitive tasks. They streamline data extraction, reconciliation, and invoice processing, significantly reducing errors. This shift empowers professionals to focus on higher-value analysis and critical judgment.
However, AI’s true potential extends beyond simple task automation. Predictive analytics offer sharper forecasts, while AI audit tools can analyze entire datasets in seconds. Anomaly detection systems can flag risks before they escalate, creating a truly proactive financial environment. These capabilities contribute to the long-sought goal of ‘continuous closing,’ where financial data updates, validates, and analyzes in real time.
Instead of waiting weeks for period-end reconciliations, organizations can maintain an always-accurate, live view of their performance. This transforms accounting from a backward-looking process into a dynamic, forward-looking intelligence system. Yet, this innovation also brings challenges, especially in an industry that demands ‘zero errors’ and complete transparency.
The Shifting Landscape of the Accounting Market
Accounting serves as the backbone of every business, from small startups to Fortune 500 giants. It converts financial complexity into clarity, ensures compliance, and supports confident decision-making. Historically, the profession relied on a billable-hours model, employing hundreds of thousands of professionals across the US and Europe.
In the US alone, over 1.4 million accountants and auditors contribute to a market exceeding $145 billion in 2025, with continued strong demand. Education pathways are also adapting; the traditional 150 credit hours for CPA licensing, for example, are under review. New skills in AI and ESG are now becoming essential, reflecting the industry’s technological evolution.
As the technological stack matures, accounting firms are gearing up for a major transformation driven by intelligent automation and data-centric innovation. Giants like PwC are investing $1 billion to scale AI capabilities across audit and tax services. Similarly, Thomson Reuters acquired Materia, specializing in agentic AI for tax, audit, and accounting professionals.
However, it’s crucial to understand that AI isn’t about robots taking over jobs. The World Economic Forum predicts AI and automation will create 58 million new jobs, primarily in high-skill roles. Historical parallels, like the introduction of bookkeeping software in the 1980s, show that new technologies transform, rather than eliminate, jobs. Tools like Intuit and Excel, for example, led to a 75% growth in accounting roles over a decade, empowering workers to handle more complex tasks.
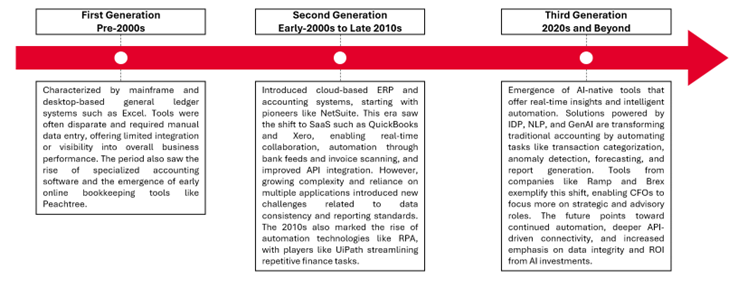
From early bookkeeping software to today’s cloud-based platforms, accounting has undergone several major phases, each marked by significant advancements in tools and capabilities.
AI’s Impact Across the Accounting Value Chain
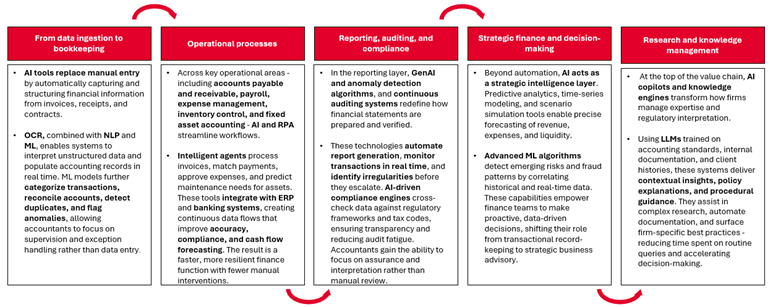
AI is rapidly transforming accounting from end to end, automating routine work, enhancing accuracy, and providing real-time financial insights. These technologies reshape how finance teams operate, from document processing to intelligent forecasting.
- Intelligent Document Processing (IDP): Combining AI, OCR, and Natural Language Processing (NLP), IDP reads, extracts, and validates data from invoices, receipts, and contracts. This dramatically reduces manual entry and improves tax and transaction accuracy.
- Chatbots & AI Agents: These tools manage queries, coordinate workflows, and generate reports. They handle vendor questions, guide staff through complex tasks, and streamline financial research. This is a prime example of how to use machine learning tools for client communication, enabling faster, more consistent responses.
- Generative AI (GenAI): GenAI produces reports, analyses, and contextual insights from large datasets. It powers smarter accounts payable/receivable processes and facilitates faster, compliant reporting.
- Machine Learning (ML): ML predicts trends, detects anomalies, and automates reconciliations. This leads to better forecasting, enhanced fraud detection, and optimized cost management.
- Robotic Process Automation (RPA): RPA executes repetitive workflows like payroll or reconciliations. AI further enhances RPA’s accuracy and adaptive decision-making capabilities.
- Natural Language Processing (NLP) & Optical Character Recognition (OCR): These convert unstructured text and documents into structured data. They extract clauses, summarize reports, and significantly improve analytics.
Together, these technologies are transforming accounting from a manual, backward-looking process into an intelligent, forward-looking engine of business insight. They collectively reshape the entire accounting value chain.
The Rise of Continuous Closing and the Evolving Accountant
A key outcome of AI’s integration is the emergence of ‘continuous closing.’ In this model, financial data is captured, reconciled, and validated continuously, rather than just at month-end. By embedding automation and intelligence into daily workflows, accounting teams can maintain always up-to-date books, offering real-time visibility into performance, liquidity, and compliance.
This evolution eliminates the traditional ‘period-end crunch,’ replacing it with ongoing accuracy and control. Machine learning and RPA automatically reconcile transactions, while GenAI generates contextual reports on demand. Anomaly detection tools ensure integrity across all systems, creating a finance function that operates continuously, not retrospectively.
Moreover, as automation handles transactional work, the accountant’s role is shifting from execution to strategic advisory and decision enablement. Instead of manual reconciliations, data entry, or compliance checks, finance professionals can focus on identifying and analyzing anomalies, interpreting insights, advising business leaders, and driving growth initiatives.
AI copilots and intelligent assistants augment human expertise, suggesting optimizations, highlighting anomalies, and surfacing insights that guide strategic choices. This transformation elevates finance from a back-office function to a central intelligence hub supporting corporate strategy in real time. Accountants are becoming data interpreters, storytellers, and risk managers, bridging financial accuracy with business foresight.
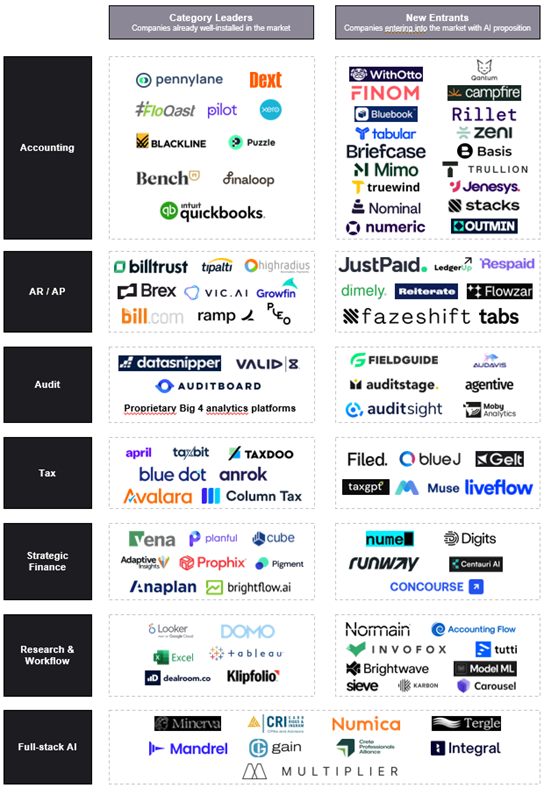
Ultimately, firms that effectively combine automation with human judgment will thrive. They leverage AI to amplify, rather than replace, financial expertise. The accounting technology landscape is evolving rapidly as AI reshapes every segment of the finance function, with both established leaders and new entrants vying for market share.
Pathways to Breaking into the AI Accounting Space
The product strategy shaping AI adoption in accounting generally follows two distinct models: AI agents and tools sold as B2B SaaS products, and full-stack AI firms operating as automated accounting practices.
The AI agent and tools model fits within the traditional enterprise software paradigm. Vendors build systems to handle tasks like reconciliation, invoicing, tax filings, or anomaly detection, licensing them to firms or finance teams. This subscription-based, continuously updated, and workflow-integrated SaaS model appeals to incumbents like the Big Four, boosting productivity without disrupting existing client relationships or fee structures.
Conversely, full-stack AI companies aim to become the accountants themselves, offering end-to-end services directly to SMEs and individuals. These firms promise faster, cheaper delivery and higher margins by compressing labor into code. Investors are backing this model, with Y Combinator encouraging ‘full-stack AI companies’ and Crete deploying over $500 million to consolidate practices. This approach seeks to entirely displace incumbents, mirroring vertical SaaS but going further.
Both models imply that accountants must evolve into roles closer to data scientists, validating AI outputs and translating insights into business decisions. Similarly, successful AI startups need embedded accountants to encode domain expertise into scalable systems. Both strategies have trade-offs: agents are capital-light but risk commoditization, while full-stack is disruptive but operationally demanding. Both will likely coexist, with incumbents adopting agents and challengers pursuing full-stack strategies.
Targeting Users: Accountants vs. End Customers
Go-to-market models also diverge, either serving accountants directly or targeting SMBs directly. Each approach influences product design, pricing, sales, and customer acquisition strategies significantly.
Companies like Pennylane or Karbon, for example, build their go-to-market strategy around serving accountants as primary customers and distribution partners. Their platforms facilitate collaboration with SME clients, acquiring over 80% of customers through accounting firms. This intermediary model creates a multiplier effect, as one accountant can bring dozens of SMEs, driving higher lifetime value through long-term client relationships and addressing complex regulatory requirements.
In contrast, firms like Finom (an AVP portfolio company) adopt a direct B2B approach, targeting business owners with their ‘by Entrepreneurs for Entrepreneurs’ AI accounting platform. These solutions prioritize user-friendly interfaces, automation, and self-service, enabling companies to manage finances without extensive professional expertise. They rely on standardized pricing, online resources, and digital marketing to reach business owners at scale.
Key Risks and Challenges in AI Accounting
Implementing AI in accounting presents significant risks, with reliability being the most immediate challenge. Generative AI systems are still prone to hallucinations, model bias, and factual inconsistencies. These issues are unacceptable in a zero-tolerance compliance environment, where even minor errors can have severe regulatory or legal consequences.
The rise of deepfakes and synthetic data also introduces reputational risks, as firms must prepare for malicious actors exploiting AI for fraud or misinformation in financial records. This raises a fundamental question of accountability: who bears ultimate responsibility for an error? Currently, regulatory frameworks place the burden on licensed professionals, meaning accountants remain legally and ethically accountable, even when using AI.
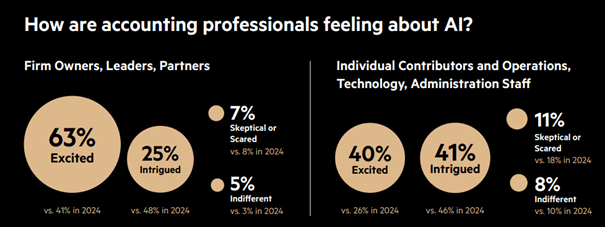
This situation pressures firms to implement robust oversight, auditability, and governance mechanisms around AI adoption. While most accounting professionals are enthusiastic about AI, some remain cautiously intrigued or even skeptical due to these concerns. Moreover, many AI initiatives falter due to a lack of contextual understanding.
Current systems often process only summary-level data, like trial balances or aggregated figures, without grasping the underlying transactions, attachments, and decision trails. Yet, this context – who made a change, why an adjustment occurred, how a discrepancy resolved – defines true accounting judgment. Without this deeper understanding, AI models may generate statistically accurate but operationally irrelevant insights.
The next generation of AI-driven accounting platforms must evolve from data ingestion to ‘context ingestion.’ They need to learn from the complete history of financial activity to deliver insights that are not only correct but also explainable. Ultimately, in accounting, real intelligence lies in how professionals manage exceptions. Every manual correction, reclassification, or override embeds valuable information about context, policy, and intent.
AI systems capable of capturing and learning from these micro-decisions can continuously refine their accuracy and adaptability. Rather than viewing human oversight as a limitation, modern accounting platforms redefine it as a feedback loop, transforming each human intervention into a data point that strengthens future automation. The result is a self-improving ecosystem where human expertise and machine learning co-evolve, driving both precision and trust.
Business Model Design and Regulatory Hurdles
Another risk lies in the business model mismatch. Traditional accounting has long structured itself around billable hours, incentivizing partners to maximize utilization. AI, by dramatically reducing the time required for routine tasks, threatens to cannibalize revenue in hourly billing departments like tax.
While automation can improve margins in fixed-fee services like audit, vendors must carefully navigate these conflicting incentives. The predictable, scalable, and volume-driven SaaS subscription model clashes with legacy revenue structures, potentially creating resistance to AI adoption within firms.
The accounting industry also operates under stringent and often fragmented regulatory regimes that differ widely across jurisdictions. This contrast is especially clear between Europe and the United States. In the US, firms operate within a highly unified framework: a single accounting standard (US GAAP), centralized oversight, consistent audit requirements, and a nationally recognized CPA credential. This coherence allows providers to scale nationally with fewer structural or regulatory barriers.
Europe, however, presents a fundamentally different landscape. While listed companies apply IFRS, each of the 27 EU member states maintains its own local GAAP, professional licensing regimes, audit oversight authorities, tax codes, VAT structures, payroll systems, and statutory reporting rules. Even with EU-wide initiatives, the practical realities of regulatory divergence remain, creating a patchwork of obligations across borders.
For AI-driven accounting solutions, these regulatory differences translate into both technical and legal constraints. Model architectures, data pipelines, and compliance controls often require country-specific customization, particularly given Europe’s stronger emphasis on auditability, explainability, and data sovereignty. These requirements, while essential for trust, widen the scalability gap between Europe and the US.
Achieving pan-European scale remains significantly more complex than scaling within the United States. In the near term, AI entrants may find it more viable to target specific verticals, market segments, or national ecosystems, refining their models to align with local standards. Over time, regulatory harmonization could narrow the gap, but today, Europe’s regulatory diversity stands as a significant constraint for any AI solution seeking cross-border deployment.
Frequently Asked Questions About AI in Accounting
Q: Will AI replace accountants?
A: No, AI is unlikely to replace accountants entirely. Instead, it transforms their roles by automating repetitive tasks, allowing professionals to focus on higher-value activities like strategic advisory, data interpretation, and complex problem-solving. AI acts as an assistant, enhancing human capabilities.
Q: How does AI improve accuracy in accounting?
A: AI technologies like Intelligent Document Processing (IDP) and Machine Learning significantly reduce manual data entry errors. They automate reconciliations, detect anomalies, and process large datasets with greater precision than human efforts, leading to more accurate financial reporting.
Q: What is ‘continuous closing’ and how does AI enable it?
A: Continuous closing is an accounting model where financial data is captured, reconciled, and validated on an ongoing basis, rather than just at period-end. AI tools like RPA and machine learning automate these daily processes, providing real-time financial visibility and eliminating the traditional ‘period-end crunch.’
Q: How can machine learning tools enhance client communication?
A: Machine learning tools, particularly through AI agents and chatbots, can manage routine client queries, provide instant information, and even generate personalized reports. This streamlines communication, ensures consistent responses, and frees up human accountants to engage in more in-depth, strategic client discussions.
Q: What are the main challenges of implementing AI in accounting?
A: Key challenges include ensuring AI model reliability and accuracy (avoiding ‘hallucinations’ and bias), adapting traditional billable-hours business models to AI’s efficiency gains, and navigating complex and fragmented regulatory environments, especially across different countries.
Keywords: AI in accounting, machine learning accounting, continuous closing, accounting automation, future of accounting, AI tools finance, client communication AI, financial technology, generative AI accounting, accounting job transformation