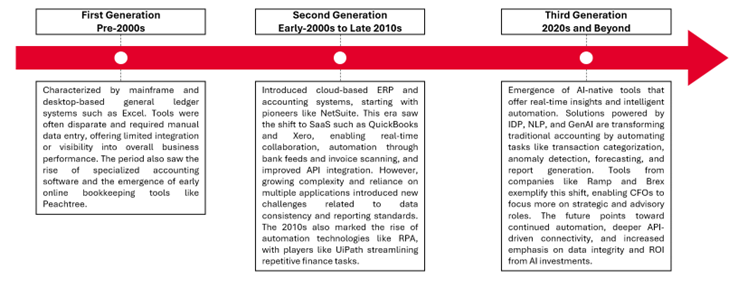
The accounting world stands at a remarkable crossroads, reminiscent of when Luca Pacioli first introduced double-entry bookkeeping in 1494. For centuries, his framework provided businesses with a clear, integrated view of their finances. Today, artificial intelligence (AI) is ushering in a similar monumental shift, poised not just to automate tasks but to fundamentally redefine the entire accounting discipline.
Accounting, with its many labor-intensive subspecialties like bookkeeping, payroll, tax, and audit, presents an ideal landscape for automation. These fields demand both accuracy and efficiency, qualities that modern AI technologies are now delivering. By leveraging AI, professionals can move beyond repetitive manual work to focus on higher-value analysis and strategic judgment, transforming a backward-looking process into a dynamic, forward-looking intelligence system.
New technologies such as Generative AI (GenAI), Optical Character Recognition (OCR), Intelligent Document Processing (IDP), and smart agents are swiftly taking over routine tasks. Think about data extraction, reconciliation, and invoice processing – AI significantly reduces errors and frees up valuable human time. However, AI’s true power extends far beyond mere task automation.
Predictive analytics, for example, can sharpen financial forecasts, while AI audit tools test entire datasets in seconds. Anomaly detection systems can even flag potential risks before they escalate. Collectively, these capabilities bring us closer to the long-desired goal of ‘continuous closing,’ where financial data updates, validates, and analyzes in real time.
Instead of waiting weeks for period-end reconciliations, organizations can maintain a live, constantly accurate view of their performance. This transforms accounting into a proactive system that provides instant insights. The market also reflects this shift, with the US accounting services sector valued at over $145 billion in 2025, showing strong and continued demand.
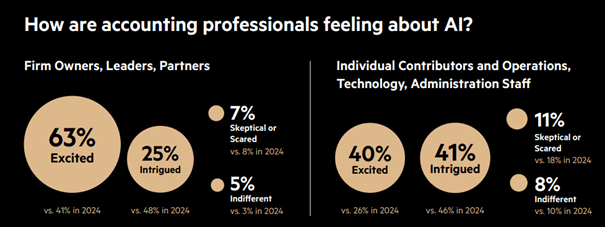
Education pathways are evolving too, with firms like KPMG re-examining traditional credit hour requirements. New essential skills in AI and ESG are increasingly important for a new generation of accountants. Major players are investing heavily; PwC, for instance, has committed $1 billion to scale AI capabilities across its audit and tax services.
AI is reshaping accounting from beginning to end, automating routine work, enhancing accuracy, and unlocking real-time financial insights. Intelligent Document Processing (IDP) combines AI, OCR, and Natural Language Processing (NLP) to read, extract, and validate data from various documents like invoices and receipts. This dramatically cuts down on manual entry and boosts the accuracy of tax and transaction records.
This is precisely how to use AI copilot for data entry automation effectively. AI-powered tools act as digital assistants, or ‘copilots,’ by handling the tedious, repetitive aspects of data entry. They analyze unstructured data, recognize patterns, and input information into systems, minimizing human intervention and potential errors.
Beyond IDP, other AI forms contribute significantly. Chatbots and AI agents manage queries, coordinate workflows, and generate reports, streamlining interactions with vendors and guiding staff through complex tasks. Generative AI produces insightful reports and analyses from large datasets, enhancing Accounts Payable/Receivable processes and ensuring faster, compliant reporting.
Machine Learning (ML) predicts trends, detects anomalies, and automates reconciliations, leading to better forecasting and fraud detection. Robotic Process Automation (RPA) executes repetitive workflows such as payroll, with AI further boosting accuracy and adaptive decision-making. These technologies together transform accounting into an intelligent, forward-looking engine for business insights.
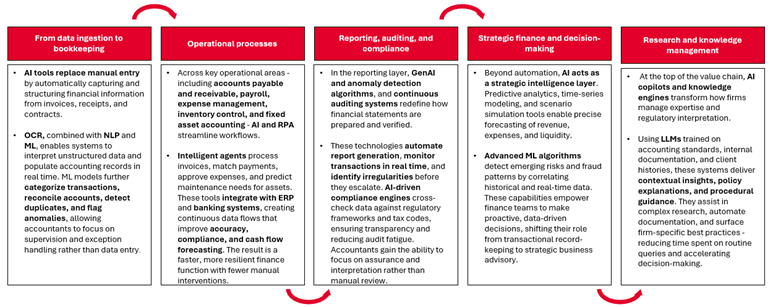
A significant outcome of integrating AI across the accounting value chain is the advent of continuous closing. This model ensures financial data is captured, reconciled, and validated constantly, rather than only at month-end. By embedding automation and intelligence into daily workflows, accounting teams keep their books perpetually updated, offering real-time visibility into performance, liquidity, and compliance.
This evolution eliminates the traditional ‘period-end crunch,’ replacing it with ongoing accuracy and control. Machine learning and RPA automatically reconcile transactions, while GenAI generates contextual reports on demand. Anomaly detection tools also maintain integrity across all systems, ensuring a proactive finance function.
Moreover, as automation handles transactional work, the role of accountants is evolving from execution to strategic advisory and decision enablement. Instead of spending time on manual data entry or compliance checks, finance professionals can focus on analyzing anomalies, interpreting insights, and advising business leaders. AI copilots and intelligent assistants augment human expertise, suggesting optimizations and highlighting insights that guide strategic choices.
This transformation elevates finance from a back-office function to a central intelligence hub supporting corporate strategy in real time. Accountants become data interpreters, storytellers, and risk managers, blending financial accuracy with business foresight. Ultimately, firms that successfully combine automation with human judgment will thrive, using AI to amplify, not replace, financial expertise.
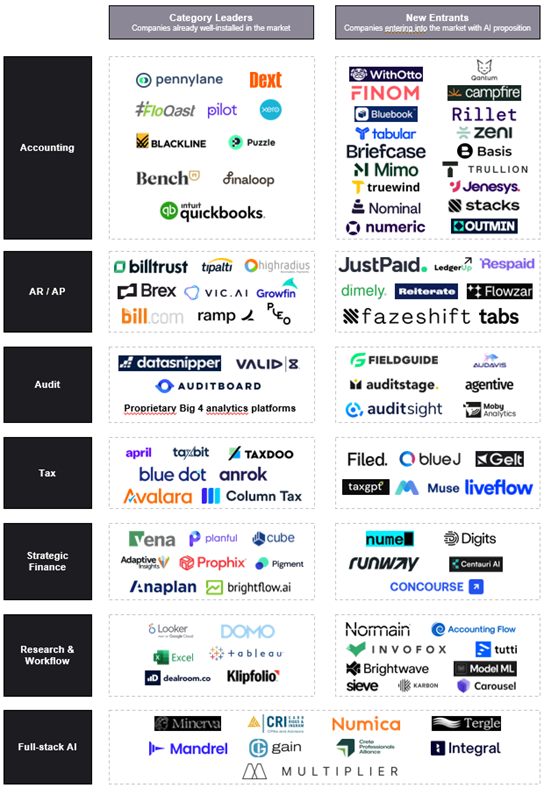
The product strategies shaping AI adoption in accounting primarily diverge into two models. First, we see AI agents and tools sold as B2B SaaS products, where vendors license systems for tasks like reconciliation or tax filings. This subscription-based approach is appealing to established firms, enhancing productivity without disrupting existing client relationships or fee structures.
Research indicates that GenAI already tackles ‘the boring stuff,’ increasing reporting granularity and freeing accountants from repetitive tasks. Conversely, full-stack AI companies aim to become the accountants themselves, offering end-to-end services directly to small and medium-sized enterprises (SMEs) and individuals. These firms promise faster, cheaper delivery and higher margins by encoding labor into software.
While the agent approach is less capital-intensive, it risks commoditization as incumbents develop in-house tools. The full-stack path is more disruptive and economically expansive but also operationally demanding, facing significant execution risks related to licensing and liability. Both models will likely coexist, with incumbents adopting agents and challengers pursuing full-stack strategies.
Similarly, go-to-market models also split between serving accountants directly and targeting SMBs. Companies like Pennylane or Karbon build their strategy around accountants as primary customers, leveraging them as distribution partners to reach numerous SMEs. This intermediary model creates a multiplier effect and helps navigate complex regulatory requirements.
In contrast, firms like Finom (an AVP portfolio company) adopt a direct B2B approach, targeting business owners with user-friendly, automated platforms. These solutions emphasize self-service, standardized pricing, and digital marketing to reach a broader audience. The choice of target user significantly shapes product design, sales strategy, customer relationships, and regulatory compliance.
Implementing AI in accounting comes with significant risks, starting with reliability and accuracy. GenAI systems can still experience ‘hallucinations,’ model bias, and factual inconsistencies. These issues are unacceptable in an industry with zero-tolerance for errors, where even minor mistakes can have severe regulatory or legal consequences.
The rise of deepfakes and synthetic data also introduces reputational risks, as malicious actors could exploit AI for fraud. This raises a fundamental question of accountability: who bears responsibility if an AI tool makes an error? Current regulatory frameworks still place the burden on licensed professionals, meaning accountants remain legally and ethically accountable for their work, even with AI assistance.
Furthermore, many AI initiatives falter due to a lack of contextual understanding. Current systems often process only summary-level data, missing the underlying transactions and decision trails that define true accounting judgment. Real intelligence in accounting lies in how professionals manage exceptions, as every manual correction or reclassification embeds valuable information about context and intent.
Modern accounting platforms are redefining human oversight as a feedback loop. Each human intervention becomes a data point, continuously refining AI’s accuracy and adaptability. This creates a self-improving ecosystem where human expertise and machine learning co-evolve, enhancing both precision and trust.
Another challenge is the business model mismatch. Traditional accounting relies on billable hours, which AI threatens by dramatically reducing the time needed for routine tasks. While automation can boost margins in fixed-fee services, the SaaS subscription model clashes with legacy revenue structures, potentially creating resistance to adoption within firms.
Regulatory hurdles and scalability also pose significant challenges. The accounting industry operates under stringent, often fragmented regulatory regimes that vary widely across jurisdictions. The US benefits from a unified framework with a single accounting standard and centralized oversight, allowing national scaling with fewer barriers.
Europe, however, presents a different landscape, with each of its 27 EU member states maintaining its own local GAAP, licensing regimes, tax codes, and reporting rules. This creates a patchwork of obligations, making pan-European scaling significantly more complex than within the United States. AI-driven solutions often require country-specific customization due to these differences, particularly given Europe’s stronger emphasis on auditability and data sovereignty.
Achieving cross-border deployment for AI solutions in Europe is much more complex, requiring adaptation rather than uniformity. In the near term, AI entrants might find it more viable to target specific verticals or national ecosystems. While regulatory harmonization could eventually narrow the gap, Europe’s regulatory diversity remains a major constraint for AI solutions seeking broad deployment.
AI is not just a tool; it’s a transformative force reshaping every segment of the finance function. While it automates the mundane, it simultaneously elevates the role of human accountants. They become strategic advisors, leveraging AI-powered insights to guide critical business decisions.
The future of accounting lies in a powerful synergy: sophisticated AI platforms handling the heavy lifting of data processing and analysis, complemented by human expertise providing judgment, context, and strategic guidance. Embracing this shift will empower accounting professionals to deliver unprecedented value, turning financial data into actionable intelligence for the modern enterprise.
Frequently Asked Questions (FAQ)
Q1: What is continuous closing in accounting?
A1: Continuous closing is an accounting model where financial data is captured, reconciled, and validated on an ongoing, real-time basis, rather than waiting for traditional month-end or period-end processes. This provides businesses with immediate, accurate insights into their financial performance.
Q2: How does AI copilot for data entry automation work?
A2: AI copilots for data entry automation leverage technologies like Intelligent Document Processing (IDP), Optical Character Recognition (OCR), and Natural Language Processing (NLP). These tools automatically read, extract, and validate data from documents such as invoices and receipts, significantly reducing manual input, errors, and processing time.
Q3: Will AI replace human accountants?
A3: While AI will automate many repetitive and transactional accounting tasks, it is not expected to replace human accountants entirely. Instead, AI transforms the accountant’s role, allowing professionals to shift their focus to higher-value activities like strategic analysis, anomaly detection, interpretation of insights, and advisory services.
Q4: What are the main challenges of adopting AI in accounting?
A4: Key challenges include ensuring the reliability and accuracy of AI systems (addressing hallucinations and bias), navigating the mismatch between traditional billable-hour models and AI’s efficiency gains, and overcoming complex, fragmented regulatory hurdles, especially when attempting cross-border deployment.
Q5: What is the difference between point solutions and full-stack AI platforms in accounting?
A5: Point solutions are B2B SaaS tools that automate specific tasks like reconciliation or tax filings, typically licensed to accounting firms. Full-stack AI platforms, conversely, aim to provide end-to-end accounting services directly to businesses or individuals, effectively becoming the automated accounting practice itself.
Keywords: AI in accounting, data entry automation, AI copilot, continuous closing, accounting automation, GenAI, OCR, IDP, future of accounting, financial technology