Accounting, a discipline rooted in Luca Pacioli’s 1494 codification of double-entry bookkeeping, currently stands at a pivotal moment. Artificial intelligence (AI) is not merely automating tasks; it’s fundamentally reshaping the entire profession. Historically, accounting subspecialties like bookkeeping, payroll, tax, audit, and advisory have been labor-intensive, making them perfect candidates for automation.
Today, AI delivers both accuracy and efficiency to these critical functions. Technologies such as Generative AI (GenAI), Optical Character Recognition (OCR), Intelligent Document Processing (IDP), and smart agents now handle repetitive tasks. They automate data extraction, reconciliation, and invoice processing, significantly reducing errors and freeing professionals for higher-value analysis.
However, AI’s true power extends beyond simple automation. Predictive analytics enhances forecasting capabilities, while AI audit tools can analyze entire datasets in mere seconds. Anomaly detection systems identify risks proactively, preventing them from escalating. These combined capabilities pave the way for ‘continuous closing,’ a long-envisioned goal where financial data updates, validates, and analyzes in real time.
Imagine maintaining an always-accurate, live view of your organization’s performance, eliminating weeks of period-end reconciliations. Accounting then transforms from a backward-looking process into a dynamic, forward-looking intelligence system. Yet, this innovation introduces challenges, particularly in an industry demanding ‘zero error’ principles.
Issues like AI ‘hallucinations’ and opaque algorithms are simply unacceptable. Successful AI adoption necessitates transparency, rigorous human oversight, and robust safeguards. Despite these hurdles, a new wave of AI startups is actively reimagining accounting, not just to cut costs but to uncover deep insights and enable strategic decision-making.
Let’s dive deeper into the current market landscape and AI’s transformative role.
Accounting forms the backbone of any business, whether it’s a small startup or a Fortune 500 company. It converts financial complexity into clarity, ensures compliance, and supports confident decision-making. The profession has traditionally relied on a billable-hours model, employing hundreds of thousands of professionals across the US and Europe.
For instance, the US alone boasts over 1.4 million accountants and auditors. The US accounting services market reached over $145 billion in 2025, and strong demand continues. Educational pathways are also evolving; firms like KPMG are re-evaluating the traditional 150-credit-hour requirement for CPA licensing. This change reflects fewer graduates entering the field and the growing need for new skills, especially in AI and ESG (Environmental, Social, and Governance).
As technology matures, intelligent automation and data-centric innovation are poised to drive a major transformation in accounting firms. Major players are already making significant investments. PwC, for example, is committing $1 billion to scale AI capabilities across its audit and tax services. Similarly, Thomson Reuters acquired Materia, a specialist in agentic AI for tax, audit, and accounting.
It’s crucial to understand that AI does not mean ‘robots are coming for our jobs.’ The World Economic Forum actually predicts that AI and automation will create 58 million new jobs, primarily in high-skill roles. Historical parallels, like the rise of bookkeeping software in the 1980s, show that new technologies tend to transform jobs rather than eliminate them.
For example, despite initial fears, tools like Intuit and Excel led to a 75% growth in accounting roles over a decade. Professionals shifted to more complex tasks, proving that technology often augments human capabilities. From early bookkeeping software to today’s cloud platforms, accounting has consistently evolved through significant technological advancements.
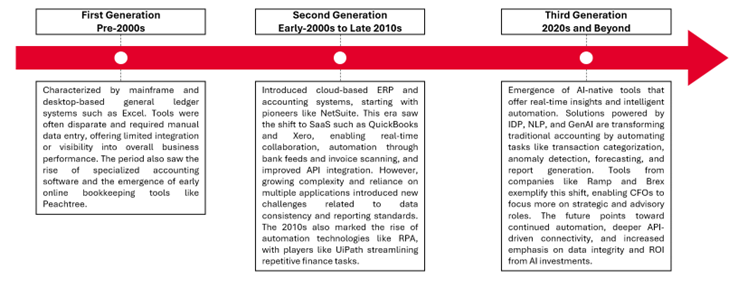
AI is rapidly transforming accounting from end to end, automating routine work, boosting accuracy, and providing real-time financial insights. These technologies are fundamentally reshaping how finance teams operate, from document processing to intelligent forecasting.
Intelligent Document Processing (IDP) combines AI, OCR, and Natural Language Processing (NLP) to efficiently read, extract, and validate data from various documents. Think invoices, receipts, and contracts. This technology dramatically reduces manual entry and significantly improves the accuracy of tax and transaction records.
Chatbots & AI Agents are becoming indispensable. They effectively manage queries, coordinate workflows, and generate reports. These tools can handle vendor questions, guide staff through complex tasks, and streamline financial research. This is where we see the best practices for AI chatbot for data entry automation truly shine. Imagine a chatbot instantly extracting details from a receipt and populating your accounting software, or validating customer information against existing records. Implementing clear guidelines for data input, robust error-checking mechanisms, and continuous training for the AI model are crucial best practices here.
Generative AI (GenAI) produces comprehensive reports, analyses, and contextual insights from vast datasets. It powers smarter accounts payable/receivable processes and enables faster, compliant reporting. Meanwhile, Machine Learning (ML) predicts trends, detects anomalies, and automates reconciliations. This leads to improved forecasting, proactive fraud detection, and optimized cost management.
Robotic Process Automation (RPA) executes repetitive workflows, such as payroll or routine reconciliations. AI then enhances RPA by improving accuracy and enabling adaptive decision-making. Natural Language Processing (NLP) and Optical Character Recognition (OCR) convert unstructured text and documents into structured data. They can extract clauses, summarize reports, and significantly enhance analytics capabilities.
Together, these technologies are converting accounting from a manual, backward-looking process into an intelligent, forward-looking engine. They generate valuable business insights, reshaping the entire accounting value chain.
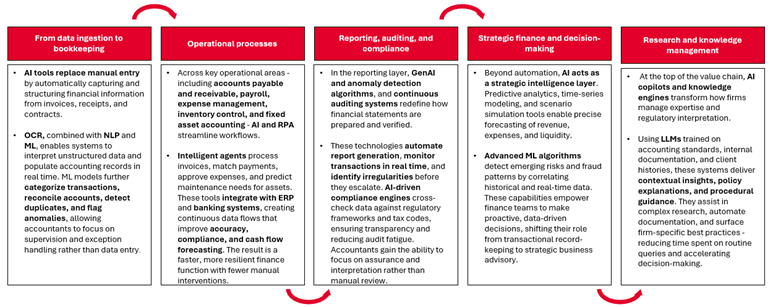
A key outcome of integrating AI across the accounting value chain is the emergence of ‘continuous closing.’ This model captures, reconciles, and validates financial data continuously, rather than just at month-end. By embedding automation and intelligence into daily workflows, accounting teams maintain always-up-to-date books.
This provides real-time visibility into performance, liquidity, and compliance, eliminating the traditional ‘period-end crunch.’ Machine learning and RPA automate transaction reconciliation, GenAI generates contextual reports on demand, and anomaly detection tools ensure integrity across systems. The finance function thus operates continuously, providing instant insights to support decision-making, strengthening governance, and driving an AI-native, real-time accounting environment.
Furthermore, as automation takes over transactional work, the role of accountants fundamentally shifts. They move from execution to strategic advisory and decision enablement. Instead of spending time on manual reconciliations, data entry, or compliance checks, finance professionals now focus on identifying and analyzing anomalies, interpreting insights, advising business leaders, and driving growth initiatives.
AI copilots and intelligent assistants augment human expertise, suggesting optimizations, highlighting anomalies, and surfacing insights that guide strategic choices. This transformation elevates finance from a back-office function to a central intelligence hub, supporting corporate strategy in real time. In this new paradigm, accountants become data interpreters, storytellers, and risk managers.
They bridge financial accuracy with crucial business foresight. Ultimately, firms that successfully combine automation with human judgment will emerge as winners. They leverage AI to amplify, rather than replace, financial expertise.
The accounting technology landscape is rapidly evolving as AI reshapes every segment of the finance function. The market map below illustrates how the ecosystem is divided between established category leaders and new entrants.
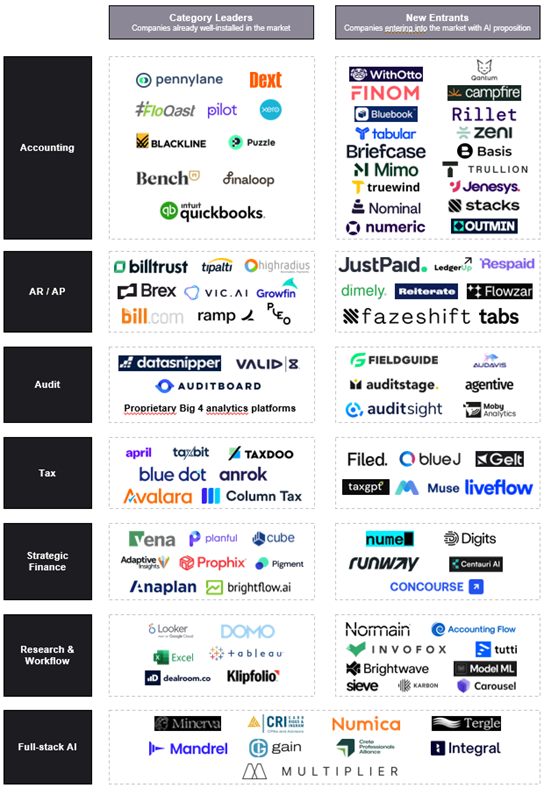
Established firms integrate AI into their mature platforms, leveraging robust user bases. New entrants, conversely, introduce AI-first propositions designed to disrupt traditional workflows.
Strategic Approaches to AI in Accounting
The product strategies shaping AI adoption in accounting primarily diverge into two models: AI agents and tools sold as B2B SaaS products, and full-stack AI firms operating as automated accounting practices.
The AI agent and tools model fits within the traditional enterprise software paradigm. Vendors build systems to handle specific tasks like reconciliation, invoicing, tax filings, or anomaly detection, licensing them to firms or finance teams. This SaaS model — subscription-based, continuously updated, and workflow-integrated — particularly appeals to incumbents like the Big Four. It boosts productivity without disrupting client relationships or established fee structures.
Research already shows GenAI ‘doing the boring stuff,’ increasing reporting granularity and freeing accountants from repetitive tasks. In contrast, full-stack AI companies aim to become the accountants themselves. They offer end-to-end services in bookkeeping, payroll, reporting, and tax compliance directly to SMEs and individuals. These firms promise faster, cheaper delivery and higher margins by essentially converting labor into code.
Some investors back this model; Y Combinator has encouraged ‘full-stack AI companies,’ and Crete, backed by Thrive Capital, is deploying over $500 million to consolidate practices. The total addressable market (TAM) here extends far beyond software licenses to encompass the full accounting revenue per customer. This strategy mirrors vertical SaaS but goes further by displacing incumbents entirely.
Similar patterns emerge in consulting, with companies like Operand building AI-native firms rather than just selling software. However, execution risk is significant. Full-stack ventures face licensing, liability, and operational complexity, as demonstrated by Atrium’s failed attempt to become the ‘AI law firm of the future.’
For both models, the implication is clear: accountants must evolve into something closer to data scientists. They will validate AI outputs and translate insights into actionable business decisions. This trend is mirrored on the vendor side, where startups cannot succeed with engineers alone; they almost always need accountants embedded in their teams to encode domain expertise into scalable systems.
Ultimately, both models present trade-offs. The agent approach is capital-light but risks commoditization as incumbents scale in-house tools. The full-stack path is more disruptive and economically expansive but also operationally demanding. Both are likely to coexist, at least initially. Incumbents will adopt agents to protect margins, while challengers pursue full-stack strategies to gain market share. The competitive outcome will depend on whether efficiency alone retains clients or if AI-native firms redefine accounting services entirely.
Target Users: Empowering Accountants vs. Serving End Customers
Just as product strategies diverge, go-to-market models also split between serving accountants directly versus targeting SMBs directly. Each approach profoundly shapes product design, pricing, sales, and customer acquisition strategies.
Companies like Pennylane or Karbon have built their go-to-market strategy around serving accountants as primary customers and distribution partners. Their platforms facilitate collaboration with SME clients, with over 80% of customers acquired through accounting firms. This intermediary model creates a multiplier effect, as one accountant can bring dozens of SMEs, while also driving higher lifetime value through long-term client relationships. It also helps address complex regulatory requirements, since accountants already manage compliance across various jurisdictions.
By contrast, other firms like Finom (an AVP portfolio company) adopt a direct B2B approach, targeting business owners with their Finom AI accounting platform. Their platforms emphasize user-friendly interfaces, automation, and self-service, enabling companies to manage finances without extensive professional expertise. These solutions rely on standardized pricing, online resources, and digital marketing to reach business owners at scale. Ultimately, the choice between targeting accountants or businesses significantly shapes product design, sales strategy, customer relationships, and regulatory compliance.
Navigating the Challenges of AI Adoption in Accounting
Implementing AI in accounting presents significant risks, with reliability being the most immediate challenge. Generative AI systems remain prone to ‘hallucinations,’ model bias, and factual inconsistencies. These issues are simply unacceptable in a compliance environment that demands zero tolerance for errors, where even minor mistakes can have severe regulatory or legal consequences.
In parallel, the rise of deepfakes and synthetic data introduces a reputational dimension. Firms must prepare for malicious actors potentially exploiting AI for fraud or misinformation within financial records. This raises a fundamental question of accountability: if an error occurs, who bears ultimate responsibility? Is it the accountant who relied on the AI tool, or the software provider who designed the system?
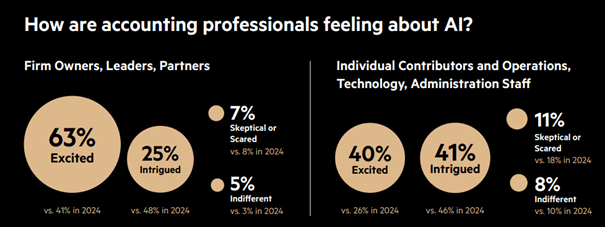
In practice, regulatory frameworks still place the burden on licensed professionals. This means accountants remain legally and ethically accountable for the accuracy of their work, even when assisted by AI. This creates additional pressure for firms to implement robust oversight, auditability, and governance mechanisms around AI adoption. It also partially explains why, despite enthusiasm, a portion of accounting professionals remains cautious or even skeptical.
Moreover, many AI initiatives in accounting falter due to a critical absence of contextual understanding. Current systems often process only summary-level data, such as trial balances, journal entries, or aggregated figures. They frequently lack comprehension of the underlying transactions, attachments, and decision trails that truly shape financial outcomes.
Yet, true accounting judgment hinges on precisely this context: who made a change, why a journal entry was adjusted, and how a discrepancy was resolved. Without this deeper layer of understanding, AI models might generate statistically accurate but operationally irrelevant insights. Therefore, the next generation of AI-driven accounting platforms or agents must evolve from mere data ingestion to ‘context ingestion.’
They need to learn from the complete history of financial activity to deliver insights that are not only correct but also explainable. Ultimately, in accounting, real intelligence doesn’t reside solely in data; it lies in how professionals manage exceptions. Every manual correction, reclassification, or override embeds valuable information about context, policy, and intent.
AI systems capable of capturing and learning from these micro-decisions can continuously refine their accuracy and adaptability. Rather than viewing human oversight as a limitation, modern accounting platforms are redefining it as a feedback loop. Each human intervention transforms into a data point that strengthens future automation, resulting in a self-improving ecosystem where human expertise and machine learning co-evolve, driving both precision and trust.
Business Model Design and Regulatory Hurdles
A second significant risk lies in the business model mismatch. Traditional accounting has long been structured around billable hours, with partners incentivized to maximize utilization. AI, by dramatically reducing the time required for routine tasks, threatens to cannibalize revenue in hourly billing departments like tax.
While automation can improve margins in fixed-fee services like audit, vendors must carefully navigate these conflicting incentives. The SaaS subscription model — predictable, scalable, and volume-driven — clashes with legacy revenue structures. This discrepancy could create resistance to adoption within firms.
The accounting industry operates under stringent and often fragmented regulatory regimes that differ widely across jurisdictions. This contrast is especially clear when comparing Europe to the United States. In the US, firms operate within a highly unified framework: a single accounting standard (US GAAP), centralized oversight by the SEC and PCAOB, consistent audit requirements, and a nationally recognized CPA credential. This coherence enables providers to scale nationally with far fewer structural or regulatory barriers.
Europe presents a fundamentally different landscape. While listed companies apply IFRS, each of the 27 EU member states maintains its own local GAAP, professional licensing regimes, audit oversight authorities, tax codes, VAT structures, payroll systems, and statutory reporting rules. Even with EU-wide initiatives such as PSD2, Peppol, and ViDA, the practical realities of regulatory divergence remain. The result is a patchwork of obligations that varies significantly across borders — in sharp contrast to the unified US environment.
This structural difference is equally visible in market dynamics. Whereas the US supports a handful of large, truly national players capable of scaling uniformly across states, Europe’s leading incumbents — such as Visma, Sage, and Cegid — are in practice federations of regional products and localized acquisitions. Others, like Fortnox, Exact, and DATEV, succeed by staying deeply rooted in their domestic markets, where regulatory nuances and localized workflows create natural moats.
In the US, a vendor can build once and distribute broadly; in Europe, successful players typically expand through adaptation, not uniformity. For AI-driven accounting solutions, these regulatory differences translate into both technical and legal constraints. Model architectures, data pipelines, and compliance controls often require country-specific customization, particularly given Europe’s stronger emphasis on auditability, explainability, and data sovereignty. These requirements — while essential for trust — further widen the scalability gap between Europe and the US.
As a result, achieving pan-European scale remains significantly more complex than scaling within the United States. In the near term, AI entrants may find it more viable to target specific verticals, market segments, or national ecosystems, refining their models to align with local standards. Over time, regulatory harmonization or interoperable compliance frameworks could narrow the gap, but today, Europe’s regulatory diversity stands in stark contrast to the US’s unified system — and remains one of the most meaningful constraints for any AI solution seeking cross-border deployment.
Frequently Asked Questions (FAQs)
Q1: How does AI enhance data entry automation in accounting?
AI significantly enhances data entry automation by utilizing technologies like OCR and IDP to extract data from documents. AI chatbots also streamline the process by handling queries and validating information, drastically reducing manual effort and errors.
Q2: What is ‘continuous closing’ in accounting, and how does AI enable it?
‘Continuous closing’ refers to a state where financial data is updated, validated, and analyzed in real time, rather than only at period-ends. AI enables this through automated reconciliation via ML and RPA, on-demand reporting with GenAI, and continuous integrity checks with anomaly detection tools.
Q3: Will AI replace accountants?
No, AI is unlikely to replace accountants entirely. Instead, it transforms their roles. AI automates repetitive tasks, allowing accountants to focus on higher-value activities such as strategic advisory, data interpretation, and risk management. AI acts as a powerful co-pilot, augmenting human expertise.
Q4: What are the main challenges for AI adoption in accounting?
Key challenges include ensuring AI reliability and accuracy (addressing hallucinations and bias), navigating clashes with traditional billable-hour business models, and overcoming complex, fragmented regulatory landscapes, particularly in regions like Europe.
Keywords: AI in accounting, data entry automation, AI chatbots, financial automation, continuous closing, generative AI, machine learning, accounting technology, financial insights, regulatory challenges